Case Study · Acquisition Financing
Gee Automotive’s Acquisition of Tuttle-Click and Jim Click
On 4/28/26, Gee Automotive (Gee) closed the acquisition of the Jim Click Automotive Team and Tuttle-Click Automotive Group (Tuttle-Click)
January 2026
Deal Summary
- On 4/28/26, Gee Automotive (Gee) closed the acquisition of the Jim Click Automotive Team and Tuttle-Click Automotive Group (Tuttle-Click)
- Funded with $300mm of 7.25% notes, pushing leverage to ~5.0x
- Tuttle-Click Highlights
- 15 dealerships and 3 collision centers
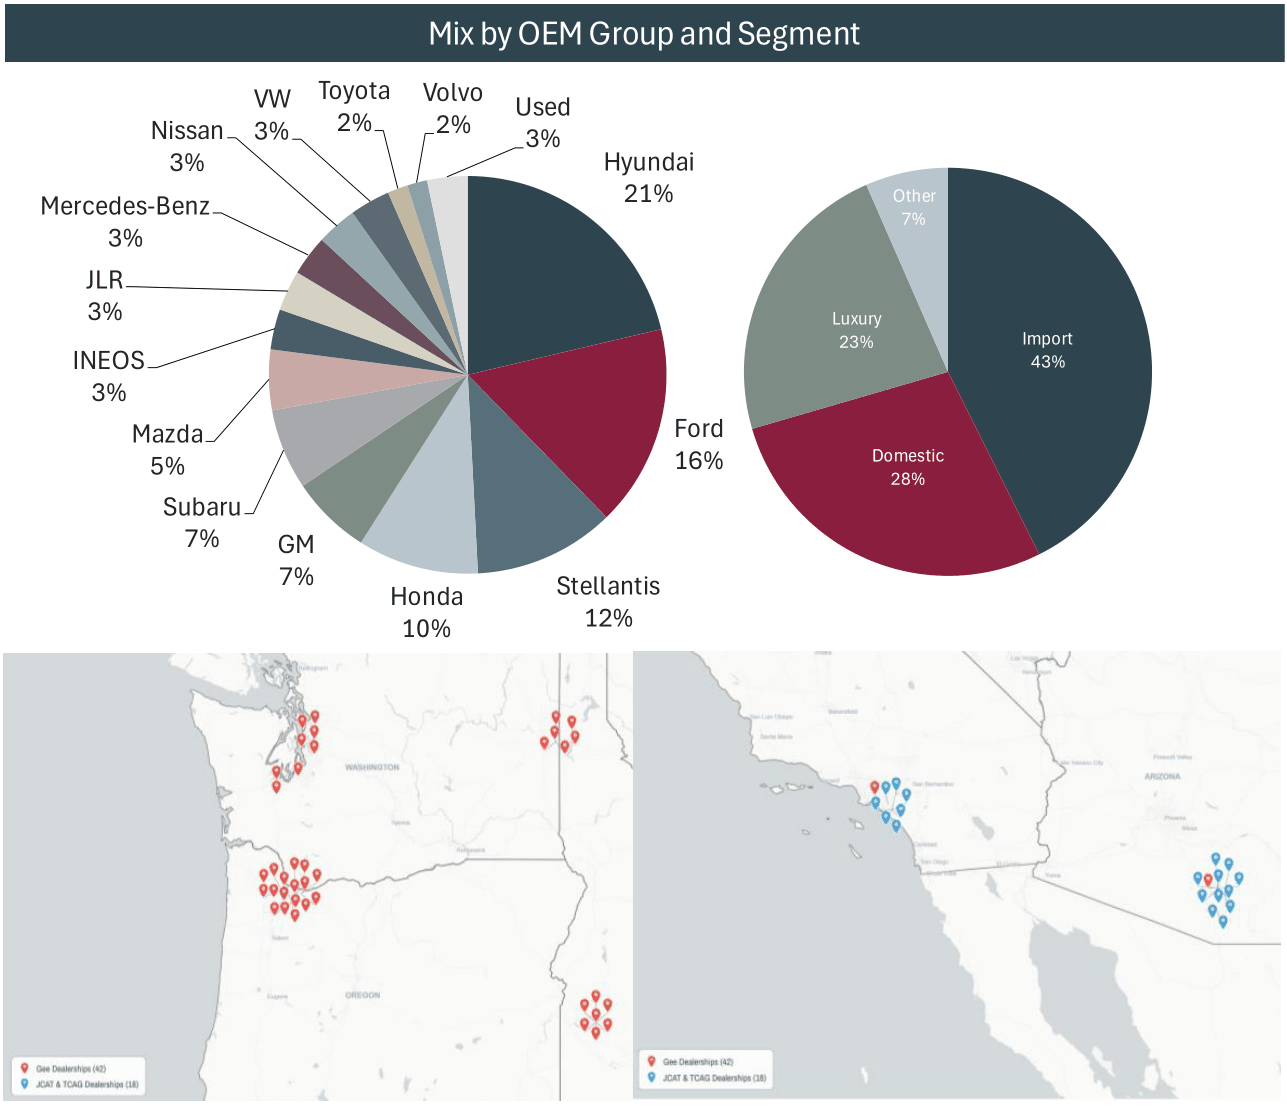
- 9 dealerships and 2 collision centers in Southern AZ
- 6 dealerships and 1 collision center in Southern CA
- 15 dealerships and 3 collision centers
- Pro Forma Combined Scale
- 75 franchises across 57 rooftops in 5 states (WA, OR, ID, CA, AZ)
- 5 collision centers in 3 states (CA, AZ, OR)
- Ownership Details
- Gee: founded by George Gee in 1983; majority owned by Bridger Holdings, a West Coast-based investment firm
- Tuttle-Click: co-owned by cousins Bob Tuttle and Jim Click Jr.; traces to Holmes Tuttle (Bob’s father)
- Both families fully exited ownership; Gee is keeping the store names and existing management
Sources: Publicly available information including S&P ratings report, press releases, and CreditSights
$300mm 5yr Senior Unsecured Notes
- Notes Issuance
- Gee funded the acquisition of Tuttle-Click with its inaugural bond offering, alongside a syndicate of lenders and an equity contribution
- On 2/9/26, Gee priced a $300mm 5yr senior unsecured notes offering with a 7.25% coupon
- Credit Profile
- Gee has a corporate rating of B+/B1 from S&P and Moody’s; its debut senior notes offering has a rating of B+/B3
- S&P forecasts ~5x leverage, $3.8bn in pro forma revenue, and a 4-4.5% adjusted EBITDA margin
- Gee’s 5yr maturity is the shortest tenor of any auto retail bonds outstanding
- Business Profile
- Gee has acquired 38 dealerships since 2012
February 2026 Notes Offering
| Sources | Amount ($mm) |
|---|---|
| Unsecured Notes Due 2031 | $300 |
| Total Sources | $300 |
| Uses | Amount ($mm) |
| Repay Existing Debt | $121 |
| Cash to Balance Sheet | 51 |
| Fund Tuttle-Click Acquisition | 128 |
| Total Uses | $300 |
| Pro-Forma Capitalization | Amount ($mm) |
|---|---|
| Cash | $50 |
| Secured Debt | 500 |
| Unsecured Notes Due 2031 | 300 |
| Total Debt | $800 |
| Pro Forma EBITDA | $160 |
| Secured Leverage | 3.1x |
| Total Leverage | 5.0x |
| Net Leverage | 4.7x |
| Final Terms | 2031 Notes |
|---|---|
| Pricing Date | February 9, 2026 |
| Issuer | Gee Automotive Holdings LLC |
| Corporate Ratings (S&P / Moody’s) | B+ / B1 |
| Bond Ratings (S&P / Moody’s) | B+ / B3 |
| Issue | Senior Unsecured Notes |
| Amount | $300mm |
| MaturityCall | March 20315yr NC2 |
| CouponSpread vs US Treasuries | 7.250%(T + 350 bps) |
| Yield to Worst (10/8/26)Spread vs US Treasuries | 7.518%(T + 249 bps) |
Yield to worst at the last institutional trade on October 8, 2026; spread vs the 5-year Treasury. The notes trade below par because Treasury yields rose ~130 bps since February, but the spread remains ~100 bps inside pricing. Joint Bookrunners - J.P. Morgan & BofA Securities
Source: Publicly available information including Moody's/S&P ratings reports and press releases; revenue, EBITDA and capitalization amounts are estimated.
Case studies are prepared by Trackhawk Advisors from the sources cited on each page. They are for information only and are not investment advice or a recommendation to buy or sell any security.